Netflix Gears Up to Report Q3 Earnings: Buy, Sell or Hold the Stock?
NetflixNFLX is slated to report third-quarter 2026 results on Oct. 20.
For the third quarter, the company forecasts revenues of $12.86 billion, implying 12% growth (11% F/X-neutral), driven by membership gains, pricing and advertising.
The Zacks Consensus Estimate for third-quarter revenues is pegged at $12.87 billion, indicating growth of 11.84% year over year.
On the profitability front, the company projects third-quarter operating margin of 33.2% versus 28.2% in the year-ago quarter.
The consensus mark for earnings is pegged at 82 cents per share. The estimate has remained unchanged over the past 30 days.
NFLX Estimate Movement
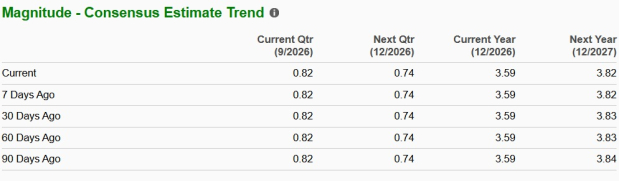
Image Source: Zacks Investment Research
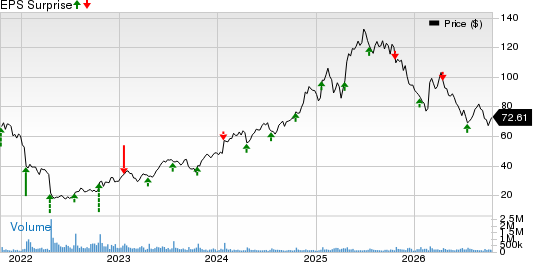
NFLX’s Earnings Surprise History
In the last reported quarter, the company delivered an earnings surprise of 1.27%. The company’s earnings beat the Zacks Consensus Estimate twice in the trailing four quarters while missing the same twice, the average negative surprise being 4.9%.
Earnings Whispers for NFLX
Our proven model does not predict an earnings beat for Netflix this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
NFLX has an Earnings ESP of +0.25% and a Zacks Rank #4 (Sell) at present.
You can see the complete list of today’s Zacks #1 Rank stocks here.
Factors Shaping Upcoming Results of Netflix
Pricing is likely to have remained a key lever in the quarter. Price changes in the United States, Mexico and Spain contributed only partially in the second quarter, when UCAN revenues rose 10%, so a full-quarter benefit is expected to have aided results. However, revenue growth was projected to decelerate from 13.4% in the second quarter, while renewed free-trial tests outside the United States and the United Kingdom might have weighed on near-term monetization. The content slate included 72 Hours with Kevin Hart, The Whisper Man, The Hawk, the final season of Outer Banks, Monster: The Lizzie Borden Story and The Gentlemen season 2. In August, Netflix added lifestyle programming from Condé Nast, Hearst and People, complementing video podcasts and creator content.
Live programming featured the Home Run Derby on July 13, MLB at Field of Dreams on Aug. 13 and a week-one NFL game in September. While live events have driven sign-ups, Netflix expected live to account for just over 5% of 2026 content spend but only about 1% of view hours, likely pressuring cost efficiency.
In advertising, Netflix concluded its 2026 U.S. Upfront in August with commitments nearly doubled, secured its first Media Rating Council accreditation for Netflix Ads Suite and made Pause Ads available programmatically across major demand-side platforms. These steps support the target of roughly $3 billion in 2026 ad revenues.
On costs, content amortization was expected to have grown more slowly in the second half, aiding margins, though technology and development expenses rose 22% in the second quarter. Capital expenditures climbed to $218.6 million in the second quarter from $155.9 million a year ago. Netflix maintained 2026 free cash flow guidance of about $12.5 billion. Second-quarter buybacks of $4.7 billion, with $27.1 billion of remaining capacity, are likely to have supported the bottom line.
Headwinds include currency volatility, intense competition from streaming rivals, including AppleAAPL, AmazonAMZN and DisneyDIS, view-hour growth of just 2% in the first half and $1 billion of debt maturing later this year. Full-year revenue guidance of $51-$51.4 billion and a 31.5% operating margin suggest steady but moderating growth.
Top-Line Growth Estimates for Q3
The consensus mark for third-quarter 2026 Asia-Pacific revenues is pegged at $1.53 billion, indicating 12.1% growth from the figure reported in the year-ago quarter.
The Zacks Consensus Estimate for Latin America revenues is pegged at $1.61 billion, suggesting a rise of 17.7% from the figure reported in the previous quarter.
Moreover, the consensus mark for EMEA revenues is pegged at $4.14 billion, suggesting an increase of 12% from the figure reported in the year-ago quarter.
The Zacks Consensus Estimate for the United States and Canada revenues is pegged at $5.57 billion, indicating an 9.9% rise from the figure reported in the year-ago quarter.
NFLX Price Performance & Stock Valuation
Shares of Netflix have plunged 22.6% in the year-to-date period compared with the Zacks Consumer Discretionary sector’s decline of 19.6%. Shares of Amazon and Apple have returned 10.2% and 25.8%, respectively, while Disney shares have lost 2.7% in the same time frame.
Netflix Underperforms Sector, Peers
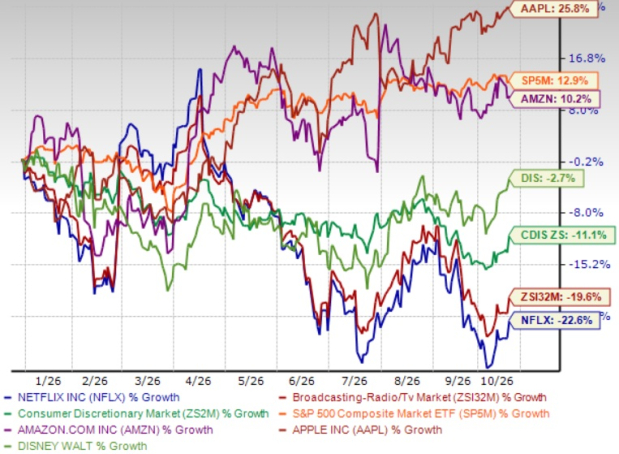
Image Source: Zacks Investment Research
Now, let’s look at the value Netflix offers investors at current levels. Currently, NFLX is trading at 5.41 times forward 12-month sales. Meanwhile, the Zacks Broadcast Radio and Television industry’s forward earnings multiple sits at 4.06 times. The company’s valuation looks somewhat stretched compared with its range and the industry average. Netflix has a Value Score of D.
Price-to-Sales (Forward 12 Months)
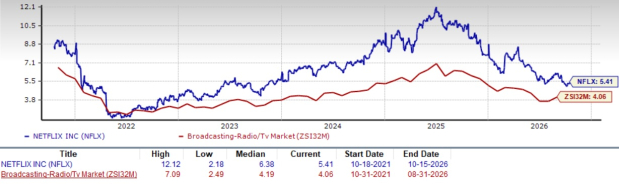
Image Source: Zacks Investment Research
Investment Considerations: Balancing Risk and Reward
Netflix’s growth engine remains intact, with third-quarter 2026 revenues guided at $12.86 billion, up 11.7% year over year, and operating margin projected to expand to 33.2% from 28.2%. Full-quarter pricing benefits, nearly doubled U.S. Upfront commitments and a roughly $3 billion 2026 ad revenue target support monetization, while $4.7 billion of second-quarter buybacks aid per-share earnings. However, decelerating revenue growth, just 2% first-half view-hour growth and rising live-programming and technology costs temper near-term upside. Stiff competition from rivals for viewing time and a premium valuation further limit the margin of safety, making the stock suited only for patient, long-term investors.
Conclusion
Netflix enters its third-quarter 2026 report with expanding margins, accelerating advertising momentum and full-year revenue guidance of $51.0-$51.4 billion. However, moderating revenue growth, stiff competition and a premium valuation limit near-term upside. Existing investors may hold the stock to benefit from pricing and ad-led gains, while new investors could wait for a better entry point after the upcoming results.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>This article originally published on Zacks Investment Research (zacks.com).
